Tag: PRIME Philippines

  • Cebu Catches its Breath as Davao Braces for a Decade’s Worth of Offices in Three Years

    PRIME’s 2026 Q3 data show Cebu’s office market navigating new supply while rents remain resilient, as Davao’s tight office and industrial markets continue to see demand running ahead of available space.

    The country’s two largest markets outside Luzon are moving through different stages of growth. PRIME Philippines’ 2026 Q3 Real Estate Market Briefing find Cebu’s office market absorbing new supply while maintaining rental resilience, and Davao preparing for its biggest wave of new office in a decade.

    Cebu Office: Slack, Not Slump – Catching its Breath, Not Losing Momentum

    Cebu’s office occupancy eased to 81.1 percent in the third quarter from 84.0 percent in the first, as net take-up turned negative by 29,400 square meters of new space was completed.

    Rents tell a more resilient story. The average office lease rate rose 3.1 percent from the first quarter to PHP 665 per square meter, above the PHP 650 recorded in 2019. Roughly 120,000 square meter of new space is slated for 2026 and 133,000 square meters for 2027, the market is entering a period where the ability to differentiate space, location, and quality will become increasingly important.

    Office Occupancy and Average Rents in Cebu and Davao, 2026 Q3

    Davao Office: A Decade in Three Years

    Davao’s office market remains one of the tightest in the country, with occupancy at 93.2 percent. Developers have noticed. From 2027 to 2029, the city will receive 145,000 square meters of new offices, nearly matching the 166,000 square meter it added over the previous nine years. this represents a major shift in the market’s supply profile. The key question will be how quickly new Grade A space is absorbed and how it changes the choices available to occupiers.

    New Office Supply in Davao City

    Demand is already running ahead. Office requirements reached 19,000 square meters from January to September, up 73 percent from 11,000 square meters a year earlier, with 15,300 square meters recorded in the third quarter alone. Corporate occupiers accounted for 63 percent of requirements, ahead of outsourcing firms and government agencies. The average rent eased 4.7 percent from the first quarter to PHP 610 per square meter as the lowest asking rate fell to PHP 330, but with quality space still limited relative to demand, PRIME expects rental levels to remain resilient as the market moves toward the arrival of new Grade A supply. The opportunity in Davao is therefore not simply about adding more office space. It is about bringing the right product to a market where established occupiers are already expanding, upgrading and evaluating their long-term requirements.

    Warehouses: Logistics leads in Both Hubs

    Cebu’s industrial vacancy edged up to 3.2 percent, yet average rents rose 3.4 percent year on year to PHP 261 per square meter. Top-end warehouse rents jumped 60 percent, from PHP 350 to PHP 560, as higher-grade facilities came online, while the floor held at PHP 100. Third-quarter requirements of 22,150 square meter were the strongest in nearly two years, led by transportation and storage firms at 79 percent of demand.

    In Davao, occupancy stands at about 95.5 percent, and the higher-grade stock has lifted the average rent to PHP 160 square meter. Requirements reached 79, 300 square meters in the first nine months, up 3 percent year on year, with transportation and storage firms accounting for 63 percent and manufacturers 27 percent. The industrial pipeline relatively lean. About 16,600 square meters is expected to come online in 2026, followed by limited new supply in 2027 and about 40,400 square meters in 2028.

    Warehouse Requirements in Cebu and Davao, January to September

    “Cebu is not slumping; it is catching its breath,” the briefing states. “Davao will get almost a decade’s worth of offices in just years, and demand is already running ahead.”

    Different Markets, Shared Opportunity

    Across VisMin, the broader story is one of continued demand meeting an evolving supply landscape. Cebu is absorbing new office and industrial space as growth expands beyond established locations, while Davao continues to operate in a tighter environment where quality supply remains highly sought after.

    For both markets, the opportunity is not simply about adding more space. It is about bringing the right product to the right locations in response to where occupiers are expanding and how their requirements are evolving.

    About PRIME Philippines

    PRIME Philippines is the country’s fastest growing and most disruptive commercial real estate advisory firm. Established in 2013, PRIME has redefined the brokerage industry by replacing outdated practices with innovation, data intelligence, and relentless execution. With full-service offices in Manila, Cebu, and Davao, PRIME has completed over 300 high-impact projects nationwide. Backed by a team over 100 professionals, PRIME is multi-awarded and trusted by the country’s top developers, investors, and occupiers. It is involved in big ticket office transactions and holds the No. 1 position in industrial leasing nationwide.

    REFERENCE: PRIME Philippines
  • Twice the Trucks, Half the Cranes: Luzon Warehouse Demand as Industrial Rents Climb in Every Market

    PRIME Philippines records 292,000 square meters of industrial requirements in 2026 Q3, up 102 percent year on year, as occupiers weigh total operating costs and developers take a more cautious approach to new supply.

    Luzon’s industrial property market strengthened in the third quarter of 2026, with PRIME Philippines recording approximately 292,000 square meters of industrial requirements, up 102 percent from about 145,000 square meters in the same quarter of 2025.

    Demand has now strengthened for two consecutive quarters after reaching approximately 116,000 square meters in 2026 Q1, signaling renewed expansion activity among industrial occupiers.

    Transportation and storage remained the largest source of classified demand at approximately 47 percent, followed by wholesale and retail trade at 19 percent and manufacturing at 18 percent. PRIME also recorded requirements from food and beverage, construction, power generation, and other service activities.

    However, PRIME sees a more important shift beyond the increase in volume occupiers are becoming more strategic and specific about the industrial properties they require.

    “Industrial demand has doubled, but what is equally important is that occupiers now have a much clearer understanding of what they need,” said Rosario, Executive Vice President for Industrial Tenant Representation at PRIME Philippines. “The decision is no longer simply about rent per square meter. Companies are looking at the total cost and efficiency of operating from a location from transportation and logistics to manpower, utilities, supply-chain access, and the technical specifications of the facility.”

    This is resulting in increasingly specific requirements for warehouse size, clear height, loading configurations, truck circulation, power capacity, accessibility, and future expansion capability.

    For many occupiers, a warehouse expansion is therefore no longer simply a real estate transaction. It is becoming a strategic supply-chain and operating decision.

    Quarterly Warehouse Demand in Luzon

    Rents Rise Across the Board

    Landlords in supply-constrained areas are raising rates as demand returns and modern facilities reach completion. Average rents year on year in all six markets PRIME tracks. Metro Manila led with a 11.8 percent increase to PHP 259 per square meter, followed by Pampanga at 5.2 percent to PHP 163 and Bulacan at 1.6 percent to PHP 180. Rents in Cavite reached PHP 248, Laguna PHP 225, and Batangas PHP 257.

    Average Industrial Lease Rates by Province, 2025 Q3 versus 2026 Q3

    Across the Luzon markets PRIME monitors, occupied industrial space stands at 40.5 million square meters, with 2.1 million square meters unoccupied, an occupancy rate of about 95 percent. Unoccupied space continues to build in Central Luzon as new completions arrive, but the market keeps absorbing them gradually.

    A Pipeline Moving Inside the Gates

    About 118,000 square meters of new warehouse space is scheduled for completion in 2017 and 268,000 square meters in 2028. Bulacan leads the 2017 pipeline 89,835 square meters as expansion spread north from Meycauayan, while Batangas accounts for 150,000 square meters in 2028. Of the 2027-2028 pipeline, 56 percent will be built inside industrial park, reflecting occupiers’ preference for quality space and the fiscal benefits of accredited parks.

    New Demand Drivers on the Horizon

    Beyond logistics, PRIME sees fresh demand from the electronics supply chain and from retailers following consumers out of the capital, as the value of production for electronics, computer, and optical products has grown by double digits year on year since October 2025, rising 17.2 percent in July 2026.

    The Philippines is fast becoming the back office of the global AI chip boom. Semiconductor exports surged 73.5 percent year on year to USD 5.2B in August 2025. They now make up roughly 85 percent of the country’s major electronic export categories. Production value for electronics, computer, and optical products has grown by double digits year on year every month since October 2025. The growth is narrow but deep, and its flavors ecozone facilities with cleanroom-ready space and reliable power over generic warehouses.

    Retailers, meanwhile, are following consumers out of Metro Manila. In 2025, CALABARZON and Central Luzon each recorded more approved construction floor area than the capital, at 8.6M and 7.9M sqm against 6.8M sqm. Central Visayas, fourth nationwide at 3.2M sqm, is emerging as the next frontier. Discount grocers and convenience chains are placing distribution centers to match. Alfamart supplies over 2,300 Luzon stores from hubs in Pampanga, Cavite, and Quezon. DALI has is a new tier of warehouse demand in secondary nodes, well beyond the traditional Metro Manila logistics belt.

    “Warehouse demand in Luzon doubled in a year as logistics firms move closer to the consumer,” the briefing states.

    Upcoming Warehouse Supply by Province, 2027-2028

    About PRIME Philippines

    PRIME Philippines is the country’s fastest growing and most disruptive commercial real estate advisory firm. Established in 2013, PRIME has redefined the brokerage industry by replacing outdated practices with innovation, data intelligence, and relentless execution. With full-service offices in Manila, Cebu, and Davao, PRIME has completed over 300 high-impact projects nationwide. Backed by a team over 100 professionals, PRIME is multi-awarded and trusted by the country’s top developers, investors, and occupiers. It is involved in big ticket office transactions and holds the No. 1 position in industrial leasing nationwide.

    REFERENCE: PRIME Philippines
  • Bigger Bills, Busier Buildings: Philippine Real Estate Holds Its Ground as a Deficit Spiral Tightens

    PRIME’S 2026 Q3 Real Estate Market Briefing finds landlords, occupiers, and investors squeezed by rising costs, even as offices, warehouses, and regional hubs kepp absorbing space.

    The Philippine economy entered the second half of 2026 under heavier strain than at midyear. The pesos closed at a record low of PHP 62.86 to the U. S. dollar on September 14, 2026. Inflation, while running at 6.1 percent in August 2026, prompted the Bangko Sentral ng Pilipinas (BSP) to raise its policy rate to 5.0 percent. The newly released September inflation reached 7.2 percent in the second quarter, and household spending rose 2.8 percent, its weakest pace since 2010 outside the pandemic.

    Yet PRIME Philippines’ 2026 Q3 Real Estate Market Briefing finds that the property market’s pain is concentrated on the cost side of the ledger, not in a collapse of demand.

    A Deficit Spiral Takes Shape

    PRIME describes the macroeconomic backdrop as a deficit spiral with three reinforcing loops. The national government’s deficit reached PHP 1.05 trillion from January 2026 to August 2026, up 21 percent year on year, as interest payments climbed 17.5 percent to PHP 686.5 billion while revenue grew only 4.27 percent. Debt reach 66 percent pf GDP at the end of June 2026, the highest since 2004. The trade deficit widened 26 percent to $41.6 billion in the first eight months as fuel imports grew costlier, foreign direct investment fell 17.8 percent in the first half, and Fitch moved its outlook on the country to negative.

    Costs, Not Demand

    PRIME’s own stakeholder survey shows where the pressure lands. Forty-eight percent of landlords name operating and financing costs as their top competitive threat, and 43 percent of occupiers cite the same costs as the war’s main effect on their business, investors rank high development cost as the number deploying capital.

    The Deficit Spiral: Three Loops Feeding a Wider Gap

    Rising Costs Top of the List of Stakeholder Concerns

    Office: Tenants Return as Supply Dries Up

    Metro Manila’s office market posted 528,000 square meters of net take-up in the third quarter, outpacing 289,000 square meters of new supply and lifting occupancy to 85.0 percent from 83.2 percent in the first half. Occupied stock reached a record 13.4 million square meters. With only 154,000 square meters due in the four quarter and 149,000 square meters in 2027, against yearly average of 667,000 square meters from 2017 to 2025, landlords are regaining leverage.

    Industrial: Warehouses Keep Moving

    Luzon warehouse requirements reached 292,000 square meters in the third quarter, more than double the 145,000 square meters a year earlier. Average rents rose in all six markets PRIME tracks, led by Metro Manila at 11.8 percent, and 65.8 percent pipeline will rise inside industrial parks.

    Visayas and Mindanao: Slack, Not Slump

    Cebu’s office leasing softened, with net take-up turning negative in the third quarter and occupancy easing to 81.1 percent, yet average rents of PHP 665 per square meter now exceed pre-pandemic levels. Davao, meanwhile, will receive 145,000 square meters of offices from 2027 to 2029, nearly the 166,000 square meters it added over the previous nine years, as office requirements jumped 73 percent in the first nine months.

    Adapting to the Squeeze

    PRIME advises consumers not to leave savings idle while inflation erodes cash, investors to consider locking in fixed-rate financing related ahead of further rate hikes, and landlords to prioritize tenant retention, since occupiers are currently absorbing the brunt of higher prices.

    “The war hit the cost of doing business, not the appetite for space,” the briefing states. “The players who adapt early will be the ones who come out ahead.”

    PRIME Philippines’s full 2026 Q3 findings, including sector breakdowns for office and industrial real estate in Metro Manila, Luzon, Cebu, and Davao, are available through PRIME Philippines Research & Advisory.

    About PRIME Philippines

    PRIME Philippines is the country’s fastest growing and most disruptive commercial real estate advisory firm. Established in 2013, PRIME has redefined the brokerage industry by replacing outdated practices with innovation, data intelligence, and relentless execution. With full-service offices in Manila, Cebu, and Davao, PRIME has completed over 300 high-impact projects nationwide. Backed by a team over 100 professionals, PRIME is multi-awarded and trusted by the country’s top developers, investors, and occupiers. It is involved in big ticket office transactions and holds the No. 1 position in industrial leasing nationwide.

    REFERENCE: PRIME Philippines
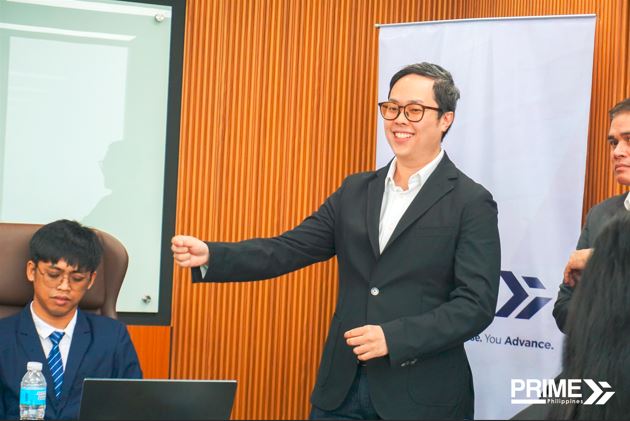
  • PRIME Philippines’ 2026 Q3 Philippine Property Market Report Media Briefing, themed “Chasing the Storm: Tracking Philippine Real Estate’s Second Wind”

    PRIME Philippines’ 2026 Q3 Philippine Property Market Report Media Briefing, themed “Chasing the Storm: Tracking Philippine Real Estate’s Second Wind”

    PRIME Philippines has presented the 2026 Q3 Philippine Property Market Report Media Briefing, themed “Chasing the Storm: Tracking Philippine Real Estate’s Second Wind” on October 7, 2026 at 32nd Floor, Mega Tower, Ortigas Center, Mandaluyong City.

    The Third Quarter Report has focused on the Office and Indusrial Sectors, as well as highlighted the Visayas and Mindanao markets.

    PRIME Philippines’ experts and speakers of the program include: Sean Chua, Manager, Research and Advisory; Mervyn Valenzuela, Vice President, Office Tenant Representation; Joy Rosario, Executive Vice President, Industrial Tenant Representation and Hannah Yoshida, Senior Head, Visayas-Mindanao.

    Dissecting the Deficit Spiral: Investigating the Threat that Defines the Next Few Years

    Sean Chua has presented this topic that is relevant to the Macroeconomy in the Philippine real Estate Market with Key Highlights that include: Elevated Fuel Cost & Headline Inflation; Declining Peso and Purchasing Power; Weaker Spending Overall; Tighter Money Environment; and Concerning Debt-to GDP Ratio.

    Room to Recover: Steady Demand Meets Stalling Supply

    Mervyn Valenzuela has shared the Office demand and supply with Key Highlights: Landlord Cut Rents to Fill Space; Professional Services Lead Office Demand; Take-up Outpaces New Supply; and Slower Pipeline Amidst High Inflation.

    Office Outlook: Vacancy to Narrow Gradually; Flight to Quality Will Split Rents; PEZA Reopening Will Support Absorption; and IT-BPM Will Shift to Higher Value.

    Twice the Trucks, Half the Cranes Industrial Demand Doubles as Developers Pull Back

    Joy Rosario has discussed the Industrial with Key Highlights that include: Explosive Growth of Semiconductor Manufacturing Fuels Industrial Demand; Wholesale and Retail Trade Will Move Outside of NCR, Following Urbanization; Lease Rates Will Appreciate From Increased Locator Appetite in NCR; and Forecasted Pipeline for 2027 declined by 72% YOY.

    Industrial Outlook: Rates to Grow by 8% to 10% in a Year; Development Pipeline to Remain Tempered; Requirements from Semiconductor Manufacturing Will Drive Industrial Growth; and Securing Present Lease Rates as Prevalent Strategy.

    Close Enough: Right Timing, Off-center for Cebu’s New Offices

    Hannah Yoshida has shared that the floodgates are opening for Cebu’s office market. The demand drivers 80% Business Process Outsourcing, 12% Traditional and 8% Gov’t for the Cebu’s Office Market. Besides, new supply will take pressure off Cebu’s core office districts, Cebu’s next wave of offices is built to go green, and Cebu’s lease rates have recovered to onset-pandemic levels.

    Slack, Not Slump: Cebu Rents Rise Through a Softer Market

    Cebu’s warehouse rents hold as vacancy edges up to 3%. The demand drivers of the Cebu’s Industrial Market are 86% Transportation & Storage; 10% Utilities; and 4% Manufacturing. Higher-end facilities lift Cebu’s average rates as the rent band holds firm. While warehousing demand maintained its pace in Cebu.

    The Next Prime Office Hub: Davao City

    More developers (SM, MEGAWORLD, GAISANO, ROBINSONS LAND CORPORATION & DAMOSA LAND) are racing to construct offices in Davao with the demand drivers of 63% Traditional, 20% BPO, and 17% Gov’t. Davao will receive nearly a decade’s worth of offices in 3 years. Davao last available offices will only get pricier from here, IT-BPM remains as the key anchor of Davao’s office market, and the scramble for Davao offices goes beyond BPO’s.

    Mindanao’s Logistics Anchor: Demand for Davao Runs Ahead of New Supply

    Davao warehouse rents sit still at PHP 160 (in sqm); Davao City remains as top location for upcoming completions in Davao Del Sur; Davao’s rent ceiling jumped to PHP 300 per sqm; and Davao’s demand show no sign of slowing down.

    Reference: PRIME Philippines

  • PRIME Philippines’ Exclusive Presentation of the Mid-Year Property Market Report titled “The Confidence Gap: Closing the Distance Between Fear and Fact”

    The PRIME Philippines’ Exclusive Presentation of the Mid-Year Property Market Report titled “The Confidence Gap: Closing the Distance Between Fear and Fact” enriched by their recent Business Confidence Survey, was held on August 5, 2026 at GreatWork, 32nd Floor, Mega Tower, Ortigas Center, EDSA, Mandaluyong City.

    This media briefing was an exclusive presentation of the Philippine Real Estate Market Overview that focuses to the Industrial, Office and Retail in the business community in relation with the prevalent situation of the economy in the Phliippines and beyond.

    During the event Mr. Jet Yu, Founder & CEO, PRIME Philippines, mentioned that PRIME fielded a real estate survey on the Middle East conflicts, impact, drawing directly from landlords, occupiers, and investors rather than relying on secondary market commentary.

    He also mentioned that the survey reflects how respondents are adjusting net income expectations , absorbing higher operating costs from inflation, and recalibrating financial strategies in response to the shock. It also captures their broader need on portfolio activity, capital markets, and outlook.

    Mr. Sean Chua, Senior Assistant Manager Research & Advisory; Sondi Tuazon, Senior Head, Tenant Representation Retail Markets; Joy Rosario, Vice President, Industrial Solutions Department; and Mervyn Valenzuela, Vice President, Tenant Representation Office Markets are one of the trusted speakers or communicators of PRIME Philippines who had shared insights of the theme or title “The Confidence Gap: Closing the Distance Between Fear and Fact”.

    Fear refers to what worries the market, and Fact refers to what the data shows in the Philippine Real Estate Market in Industrial, Office, Retail and the economy of the country. With the unsold condo “inventory” (79K-81K) in NCR (2026H1), investor appetite for condos has dropped significantly due to the “condo crisis”. But the fact is 37.5% (81K) of the unsold units are ready-for-occupancy. Vacancies are concentrated in Pasay, Paranaque, and Muntinlupa. Most unsold inventory is under construction or unbuilt.

    What also worries in the market is 1/3 of jobs exposed to AI displacement. The BPO sector faces the highest AI-related job risk, according to IMF. In fact, what the data shows is 2M AI-enabled BPO workers (2028 target). The BPO industry closed 2025 with revenue, up 5% year-on-year in 2025. (BPAP targets to augment the BPO talent pool to expand global capability centers.

    FEAR (What worries in the market): 7.2% increased of Inflation rate (April 2026). Diesel prices rose 111% since the conflict began. Gasoline prices increased 71.6% over the same period. FACT (What the data shows): PHP 344.6 B increase in value of certified renewable projects in 2026. (BOI). Inflation pressures were also seen in Vietnam, the US, and the Eurozone. The DOE has also fast-tracked 1,471 MW of renewable energy capacity.

    FEAR (What worries in the market):2.8% decrease of GDP growth, weakest since pandemic (2026Q1). Consumer confidence fell to -42% in 2026Q2. Slower growth and weaker sentiment may weigh on retail recovery. FACT (What the data shows): >90% of average occupancy of major malls (2025FY – 2026H1). Expansions are continuous for F&B, grocery, convenience, and health formats as well.

    FEAR (What worries in the market): 30% decline in oil flow through Hormuz. Higher energy costs threaten industrial sector growth. Supply chain risks could weigh on logistics demand. FACT (What the data shows): 95.2% warehouse occupancy recorded in 2026H1. Over 300,000 sqm of warehouse space was completed in 2026H1. E-commerce-driven demand continues to support the sector. Pent-up demand to beef up inventories.

    The 2026 PRIME Philippines compendium Survey.

    PRIME Philippines asked landlords, occupiers, and developers how they are reading the market right now. Below is the preliminary results.

    Market Shocks Pressure Businesses, but Net Income Impact Remains Modest.

    Ongoing shocks have weighted on business performance, with 33.4% of respondents reporting declines in net income compared to 190% reporting gains, a ration of about 1.8 to 1. Gains were concentrated almost entirely among landlords and occupiers. Landlords accounted for 62.5% of all gains reported and occupiers for the remaining 37.5%, while no investors in the sample reported a net income gain. Even so, overall impact remained modest: 88.1% experienced changes of 10% or less, and only 11.9% reported substantial gains or losses.

    Despite Disruptions, Stakeholders Remain Bullish on the Market

    Confidence tilted toward the positive amid ongoing economic disruptions, with respondents clustering at neutral- to-optimistic scores and outnumbering pessimistic ratings by roughly four to one. Sentiment was measured rather than exuberant, peaking at slightly optimistic rather than the highest end of scale.

    Confidence grows when perception is tested against evidence. This publication examines the Philippine industrial, office and retail markets to identify where uncertainty ends and informed opportunity begins. Risk. Vacancy. Uncertainty. Inflation. Evidence creates Confidence.

    PRIME Philippines is the leading commercial real estate consultancy firm, founded on integrity and equipped with the most advanced technology and unparalleled industry knowledge.

    PRIME Philippines moves your business forward by incorporating the most innovative solutions to your ever-changing real estate needs. A real estate consultancy firm ready to provide your business with solutions regardless of the stage you are in.

    REFERECE: PRIME Philippines

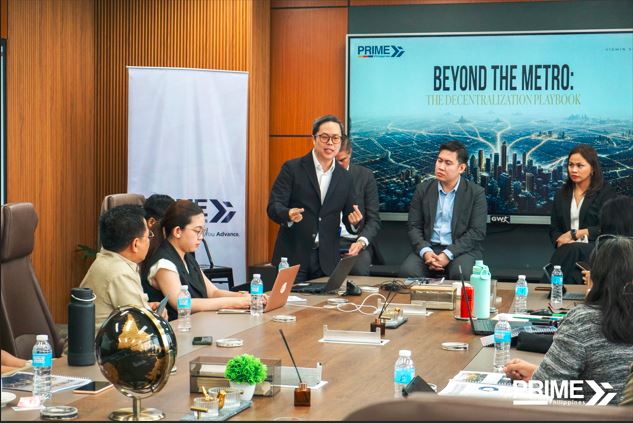
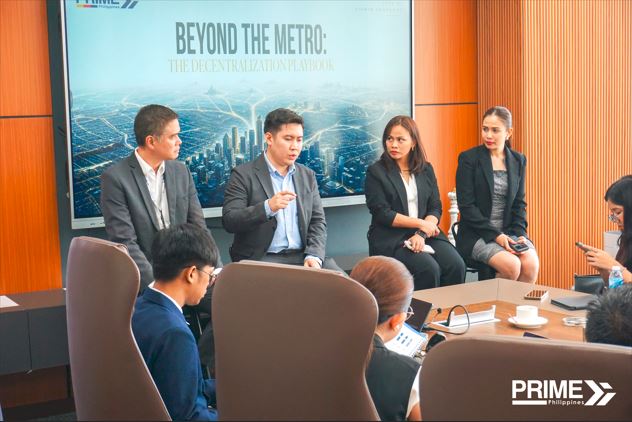
  • PRIME Philippines’ 2026 Special Property Market Report –  “BEYOND THE METRO: THE DECENTRALIZATION PLAYBOOK “

    PRIME Philippines’ 2026 Special Property Market Report – “BEYOND THE METRO: THE DECENTRALIZATION PLAYBOOK “

    PRIME Philippines’ 2026 Special Property Market Report, titled “BEYOND THE METRO: THE DECENTRALIZATION PLAYBOOK”, focuses on the Industrial and Offices Sectors as well as highlighting the Visayas and Mindanao markets, in response to the evolving backdrop due to the Middle East Conflict.

    PRIME PHILIPPINES’ Cholo Florencia, Executive Vice President, Overview; Joy Rosario, Vice President, Industrial Tenant Representation; Mervyn Valenzuela, Vice President, Office Tenant Representation; and Ruth Coyoca, Vice President, Visayas-Mindanao, are the speakers of the media briefing that was held on May 12, 2026 at GreatWork, 32nd Floor, Mega Tower, Ortigas Center, Mandaluyong City.

    The Key Macroeconomic Highlights of the Overview of Global Shockwaves, Local Impacts are GDP Driver Slowdown, Inflation Spike and Interest Tightening, Employment Decline, Credit Rating Tempering and Piecemeal Peace.

    Year-on-Year GDP Growth continues to decline from 2022 to 2026 Q1. Inflation is accelerating; policy rate increases to follow from 2021 to 2026 Q1. Employment rate reaches annual post-pandemic low from 2024 to 2026 Q1. OFW remittance are expected to decline 7.8% in 2026. Credit Rating Agencies downgraded their outlook for the Philippines .

    PEZA surpasses its full-year 2025 investment target. Foreign direct investments decline by 17.1% YOY in 2025. The Philippines’ purchasing power eroded at the quickest pace among the ASEAN-5.

    Regardless of the war outcome, the impact is predictable. Will the ceasefire hold? Scenario 1: Peace, Scenario 2: Escalation, and Scenario 3: Uneasy Ceasefire. The General Impact include Economic Slowdown, Accelerated Inflation, Short-Term Storage Demand Spike, Wait-and-See Approach and Shift Toward Renewable Energy.

    Wait and See: What Geopolitical Conflict Means for the Industrial Sector

    Steady Supply Growth to 2028, Downtick in Occupancy in 2026Q1, Flight to quality for Grade A Facilities, Lease Rates Remain Stable, and Transportation Logistics Dominate Industrial Requirements are the Key Highlights for the Industrial Sector.

    Batangas market recovers from dip as other provinces remain stable in relation with the Quarterly Warehouse Occupancy Levels per Major Corridor from 2025Q1 to 2026Q1.

    Lease rates experienced minimal changes from 2025Q4 to 2026Q1. Wholesale/Retail demand tapered off following 2025H2 as Laguna continues to top charts for requirements. Industrial warehouse lease rates have yet to follow suit as the CMPI soars due to worldwide tensions.

    Supply expansion and evolving lease strategies are expected to define the Philippine Industrial market for 2026.

    Recuperation Amid Rising Competitive Pressure

    Key Highlights for Metro Manila’s Office Sector include No major shocks in Q1, CBDs marginal softening, Typical Demand Drivers, Decentralization & Cost Shift, and Incoming Supply Pressure.

    Occupancy in Metro Manila is expected to progress gradually while new supply enter the market. Each CBD displayed varying occupancy changes QoQ amidst minimal completions. Occupancy mostly held steady in Q1 21026 in Metro Cities (Makati CBD, BGC, Ortigas CBD, Quezon City, Bay Area, Alabang CBD).

    Metro Manila CBD’s exhibited a mixed lease rate performance in Q1 2026. BGC/Makati has the Widest Rage with Ceiling Price of PHP 1,800/SQM. Alabang CBD (PHP 500 Spread)has the Tightest Range with Lowest Rate of PHP 350/SQM.

    Requirements in Q1 2026 were concentrated in CBD’s attractive to BPO and Gov’t.

    Office demand remains expansion-led

    Leasing Behavior – Demand is driven by expansion (60) rather than relocations. Hybrid and flexible arrangements were adapted particularly by the government sector, while private firms revert to dedicated setups, treating flexibility as tranasiitonal.

    Lease Terms and Preferences – Standard lease terms remain around 3 years to 5 years with some tenants preferring 5-year terms. Rising construction and fit-out costs have pushed tenants toward fitted spaces.

    Market Shifts and External Pressures – Decentralization remains additive, with firms expanding beyond core CBDs. BPO growth outside Metro Manila is concentrated in established Tier 1 and Tier 2 cities, as security, infrastructure, and incentive gaps temper Tier 3 confidence. The Fuel Crisis has impacted tenant decision and deal timelines, not negotiated lease rate.

    Cautious optimism shapes Metro Manila’s office market outlook for 2026.

    Office supply in Metro Manila is expected to grow by approximately 2.2% by the end of 2026. Tenants are increasingly preferring fitted office spaces due to rising construction costs. Occupancy is projected to improve gradually by around 1% driven by continued BPO expansion. BGC and Makati are expected to experience stable to moderate rental growth.

    Beyond the Metro: The Decentralization Playbook

    What Top Developers See in VISMIN

    Competitive wages and significant population growth supports long-term growth prospects. VISMIN has a growth-investment gap. 2025 PH Regional Investment Share, GDP Growth, and Total Population

    Different Strokes: The Diverging Trajectories of Cebu’s Key Sectors

    High leasing velocity is expected for new office developments as older developments perpetuate majority of 13.2% vacancy. Robust office pipelines are expected to accelerate 2026’s lease rate growth. Continues demand and influx of new warehouse sustain warehousing lease rate growth. The Warehouse Demand by Industry in Cebu (2025) of the 44,000 SQM include Manufacturing (28%), Transportation and Storage (27%), Wholesale and Retail Trade (25%) and Others (20%). At 2% vacancy, Cebu’s cold storage market has never been tighter.

    Industrial decentralization is creating hotspots in Cebu.

    From Cane to Capital: Why Major Developers are Betting Big on Bacolod

    Retail giants are converging on Bacolod, with approximately 100,000 sqm of new mall space expected to enter the market within the next three years.

    Solid economic fundamentals have attracted significant developer interest. GDP Growth of Highly Cities in Visayas (2024) The cities: Tacloban City (8.20%), Bacolod City (7.70%), Iloilo City (7.10%), Mandaue City (6.90%) snd Lapu-Lapu City (6.5%). National Average: 5.7% Population by Highly Urbanized City in Visayas (2024) include Cebu City (965K), Bacolod City (625K), Lapu-Lapu City (498K), Iloilo City (474K), Mandaue City (364K) and Tacloban City City (259K).

    The 100,000 sqm of new retail space of Robinsons Place Bacolod, Megaworld Upper East Mall and Rockwell Power Plant Mall will be introduce within 3 yrs.

    Office occupancy at 74.7% leaves a lot to be absorbed, but newer developments exhibit remarkable absorption underpinned by demand chiefly from the IT-BPM sector. IT-BPM Companies Present in Bacolod City inclide concnetrix, Transcom, pentagon, TQVS, APEXREVA, iqorCXBPO, HitRate, Next Level IT Teleservices, SERV CE FIRST, GlobalStrategic, T, ttec, and PROMINENT OUTSOURCE.

    Bacolod’s warehousing quality gap keeps lease rates on the lower end.

    Green All-Around: Why Mindanao is Set For Monumental Growth

    Anchored by a well-established IT-BPM sector that accounts for roughly 75% of office requirements, Davao is poised to swiftly absorb the approximately 85k sqm of new office space expected to complete within the next four years.

    CDO & Davao are the most fiscally productive HUC per capita in Mindanao. New office developments will break a 5-year streak of inactivity.

    With a saturated downtown, an emerging uptown is sprouting. Downtown Retail Developments in Cagayan de Oro include SM CITY CDO, Gaisano Mall, Centrio Mall, Limketkai Mall, Robinons and All Home.

    85k sqm of grade A office space will be introduced from 2026-2029. Davao is statistically the only landlord’s office market. IT-BPM expansion is the key driver of Davao’s office market. Office Occupants in Davao City (2026Q1) include IT-BPM (25%) and Traditional (75%) for the 284,000 SQM. Further rent segmentation will follow introduction of new developments. Davao posts one of the lowest warehouse nationwide at 2.4% with rent appreciation expected to follow. Temperature-controlled logistics have responded to rising port activity.

    VISMIN markets are expected to improve, each at their own pace

    CEBU – Robust office pipelines are expected to accelerate office lease rate growth beyond 2.4% and furthers segment premium vs. non-premium markets. Decentralization of newer supply is slated to create new hotspots in the Cebu Fringe, Southern Cebu, and other areas as vacancy is at its tightest.

    BACOLOD – The additional 100k sqm of mall space in the next 3 years will intensify pressure against local developments. The completion of Panay-Guimaras-Negros Island Bridges will help alleviate ferry dependency and create a new industrial hotspot in Pulupundan.

    DAVAO – New Grade A office completions (2026-209) amounting to 85k sqm will trigger a flight-to-quality cycle attracting new entrants into the market. Further warehouse completions are likely to delayed by rising construction cost (30%+) further prolonging the landlord’s market.

    CDO – The Uptown Corridor will emerge as CDO’s primary zone for commercial growth with the influx of various township developments. Port-linked cold storage demand is expected to grow as the Mindanao Container Terminal continuous to be over capacitated and upgraded.

    PRIME Philippines moves your business forward by incorporating the most innovative solutions to your ever-changing real estate needs. A real estate consultancy firm ready to provide your business with solutions regardless of the stage you are in.

    REFERENCE: PRIME Philippines, PRIME Philippines Research & Advisory Group

  • The Last Trophy Property on C-5: A Rare Development Site with Eastwood Lineage

    The Last Trophy Property on C-5: A Rare Development Site with Eastwood Lineage

    This high-visibility C-5 site offers the scale, timing, and conditions that have historically enabled billion-peso developments.

    C-5 Trophy Site: Where the Next Empire Begins

    Before Eastwood City became a landmark, it was land assembled with conviction during a period of national uncertainty.

    After the EDSA People Power Revolution, Andrew Tan courageously entered the real estate industry by founding Megaworld in 1989. Success followed through disciplined vision rather than immediate dominance.

    By the mid-1990s, Megaworld began developing Eastwood City, an ambitious master-planned township that redefined urban development in the Philippines.

    Then came a defining test.

    The Asian Financial Crisis hit during Eastwood’s development phase.

    Capital became scarce, and confidence declined, leading to stalled or abandoned projects across the region.

    Eastwood continued.

    Eastwood was not created by crisis, but its resilience was proven during its peak.

    The foundations of a real estate empire were established under the pressure of the crisis.

    A bold land acquisition evolved into the country’s first cyberpark, a “live, work, play, learn” ecosystem that became the birthplace of the Philippine BPO industry and generated significant long-term value.

    A Familiar Pattern, Reappearing Along C-5

    Today, a similar opportunity is available.

    Along C-5, which is emerging as Metro Manila’s parallel growth corridor to EDSA, is one of the most visible undeveloped parcels: a 62-meter frontage site with scale, access, and immediate development potential.

    This site is positioned as the C-5 Trophy Property.

    Its value comes not only from scarcity but also from its lineage.

    This site shares the same early land-assembly origins as Eastwood, established before the market recognized its potential.

    A Corridor at an Inflection Point

    Opportunities like this arise during periods of transformation, before the market fully reflects their value.

    C-5 is entering that phase.

    Once considered a secondary route, C-5 is now evolving into a parallel growth corridor to EDSA, driven by infrastructure expansion, greater interconnectivity, and the entry of institutional capital.

    What is unfolding is not incremental.

    It is structural.

    Traditional uses no longer define land along this corridor. Instead, its value is determined by what it can immediately support at scale, such as data infrastructure, logistics, or institutional campuses.

    In this environment, only a few sites have the characteristics to keep pace with today’s capital.

    The C-5 Trophy Property is one of them.

    The Three Layers of Value

    The C-5 Trophy Property stands out not only for its location but also for its layered value:

    1. Institutional Value

    A sizable, flexible parcel that can support multi-phase, large-scale development.

    2. Legacy Value

    A direct connection to Eastwood’s early land assembly, which has proven to be a wealth multiplier.

    3. Emotional Value

    Established destination behavior generates consistent foot traffic and lasting place recognition.

    A Different Kind of Buyer

    This site does not lend itself to traditional development approaches.

    It is intended for:

    • REIT-backed developers pursuing scale and yield
    • Data center and infrastructure operators requiring immediate execution

    In other words:

    Buyers who recognize value before the market validates it.

    The Real Question

    The question is no longer:

    What is this property worth today?

    The better question is:

    What does this site become in the hands of the right capital?

    Because before Eastwood became Eastwood, it was simply land, waiting for conviction.

    Closing Thesis

    The last time a site like this was assembled, it created an empire.

    This time, it is being offered as one.

    C-5 Trophy Property.

    Where the next empire begins.

    Investors and buyers considers the location, design, structural, and other factors of a certain real estate property in the diverse city.

    For Inquiries

    This property is presented to a select group of investors, developers, and institutional buyers.

    For more information, detailed materials, or to arrange a private discussion, please contact:

    CATHRINA TANTAMCO

    Commercial Property Investment

    PRIME Philippines

    +63998 845 0943

    REFERENCE: PRIME Philippines

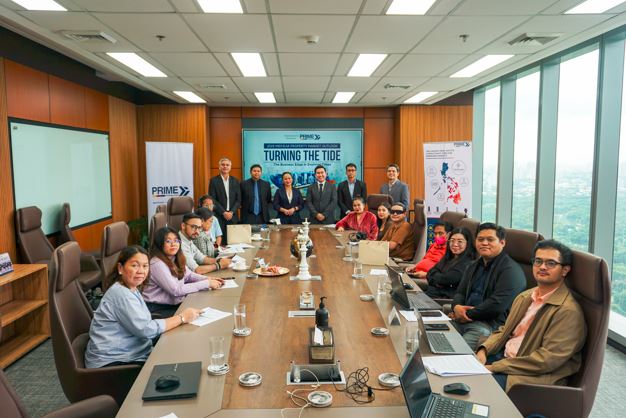
  • PRIME Philippines 2025 Media Briefing on the Mid-Year Philippine Real Estate Outlook: ”  Turning the Tide: The Business Edge in Evolving Times”

    PRIME Philippines 2025 Media Briefing on the Mid-Year Philippine Real Estate Outlook: ” Turning the Tide: The Business Edge in Evolving Times”

    The PRIME Philippines 2025 Media Briefing on the Mid-Year Philippine Real Estate Outlook entitled “Turning the Tide: The Business Edge in Evolving Times,” was held on August 7, 2025 at 2:00 PM, at GreatWork, 32nd Floor, Mega Tower, Ortigas Center, Mandaluyong City.

    In this in-person session, PRIME presented the following topics:

    1. 2025 Mid-Year Real Estate Market Performance
    2. Property Market Outlook for the remainder of 2025 and beyond

    This event is exclusively organized for their valued media partners, as they shared timely and relevant market perspectives with the press community.

    PRIME Philippines has organized and hosted the event for their valued media partners, as they shared where Philippine real estate finds strength in 2025. They shared the Industrial Market Update (Clustering-effect defines the industrial demand in 2025); Office Market Updated (Where the next office boom begins – beyond the orbit of Metro Manila);and Retail Market Update (Reshaping Retial: Evolving Formats, New Occupiers, and Regional Growth);

    Read more: https://www.duldulao.net/2025/08/08/turning-the-tide-where-philippine-real-estate-finds-strength-in-2025/

    Reference & Media Contact:

    Jullianne Mourise Dizon
    Jr. Research Analyst

    09176288341

    jullianne.dizon@primephilippines.com

    www.primephilippines.com.

    Hadassah Marie Macatangay

    #PRIMEPhilippines#PRIME#RealEstatePhilippines#RealEstate#GreatWork#OfficeMarketUpdate#RetailMarketUpdate#IndustrialMarketUpdate#RealEstateMarketingConsultant#DuldulaoDotNet#DuldulaoDotNetThisDayAndBeyond#DuldulaoDotNetMediaRepresentationServices