PRIME Philippines has presented the 2026 Q3 Philippine Property Market Report Media Briefing, themed “Chasing the Storm: Tracking Philippine Real Estate’s Second Wind” on October 7, 2026 at 32nd Floor, Mega Tower, Ortigas Center, Mandaluyong City.
The Third Quarter Report has focused on the Office and Indusrial Sectors, as well as highlighted the Visayas and Mindanao markets.
PRIME Philippines’ experts and speakers of the program include: Sean Chua, Manager, Research and Advisory; Mervyn Valenzuela, Vice President, Office Tenant Representation; Joy Rosario, Executive Vice President, Industrial Tenant Representation and Hannah Yoshida, Senior Head, Visayas-Mindanao.
Dissecting the Deficit Spiral: Investigating the Threat that Defines the Next Few Years
Sean Chua has presented this topic that is relevant to the Macroeconomy in the Philippine real Estate Market with Key Highlights that include: Elevated Fuel Cost & Headline Inflation; Declining Peso and Purchasing Power; Weaker Spending Overall; Tighter Money Environment; and Concerning Debt-to GDP Ratio.
Room to Recover: Steady Demand Meets Stalling Supply
Mervyn Valenzuela has shared the Office demand and supply with Key Highlights: Landlord Cut Rents to Fill Space; Professional Services Lead Office Demand; Take-up Outpaces New Supply; and Slower Pipeline Amidst High Inflation.
Office Outlook: Vacancy to Narrow Gradually; Flight to Quality Will Split Rents; PEZA Reopening Will Support Absorption; and IT-BPM Will Shift to Higher Value.
Twice the Trucks, Half the Cranes Industrial Demand Doubles as Developers Pull Back
Joy Rosario has discussed the Industrial with Key Highlights that include: Explosive Growth of Semiconductor Manufacturing Fuels Industrial Demand; Wholesale and Retail Trade Will Move Outside of NCR, Following Urbanization; Lease Rates Will Appreciate From Increased Locator Appetite in NCR; and Forecasted Pipeline for 2027 declined by 72% YOY.
Industrial Outlook: Rates to Grow by 8% to 10% in a Year; Development Pipeline to Remain Tempered; Requirements from Semiconductor Manufacturing Will Drive Industrial Growth; and Securing Present Lease Rates as Prevalent Strategy.
Close Enough: Right Timing, Off-center for Cebu’s New Offices
Hannah Yoshida has shared that the floodgates are opening for Cebu’s office market. The demand drivers 80% Business Process Outsourcing, 12% Traditional and 8% Gov’t for the Cebu’s Office Market. Besides, new supply will take pressure off Cebu’s core office districts, Cebu’s next wave of offices is built to go green, and Cebu’s lease rates have recovered to onset-pandemic levels.
Slack, Not Slump: Cebu Rents Rise Through a Softer Market
Cebu’s warehouse rents hold as vacancy edges up to 3%. The demand drivers of the Cebu’s Industrial Market are 86% Transportation & Storage; 10% Utilities; and 4% Manufacturing. Higher-end facilities lift Cebu’s average rates as the rent band holds firm. While warehousing demand maintained its pace in Cebu.
The Next Prime Office Hub: Davao City
More developers (SM, MEGAWORLD, GAISANO, ROBINSONS LAND CORPORATION & DAMOSA LAND) are racing to construct offices in Davao with the demand drivers of 63% Traditional, 20% BPO, and 17% Gov’t. Davao will receive nearly a decade’s worth of offices in 3 years. Davao last available offices will only get pricier from here, IT-BPM remains as the key anchor of Davao’s office market, and the scramble for Davao offices goes beyond BPO’s.
Mindanao’s Logistics Anchor: Demand for Davao Runs Ahead of New Supply
Davao warehouse rents sit still at PHP 160 (in sqm); Davao City remains as top location for upcoming completions in Davao Del Sur; Davao’s rent ceiling jumped to PHP 300 per sqm; and Davao’s demand show no sign of slowing down.
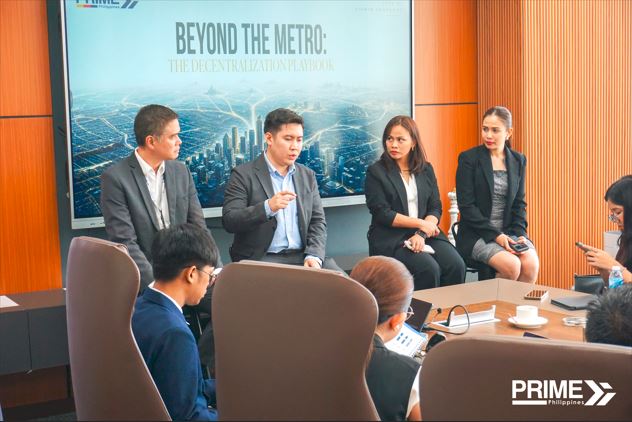
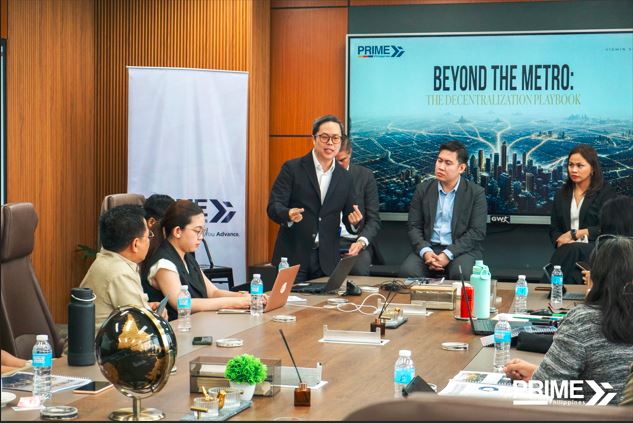
PRIME Philippines’ 2026 Special Property Market Report, titled “BEYOND THE METRO: THE DECENTRALIZATION PLAYBOOK”, focuses on the Industrial and Offices Sectors as well as highlighting the Visayas and Mindanao markets, in response to the evolving backdrop due to the Middle East Conflict.
PRIME PHILIPPINES’ Cholo Florencia, Executive Vice President, Overview; Joy Rosario, Vice President, Industrial Tenant Representation; Mervyn Valenzuela, Vice President, Office Tenant Representation; and Ruth Coyoca, Vice President, Visayas-Mindanao, are the speakers of the media briefing that was held on May 12, 2026 at GreatWork, 32nd Floor, Mega Tower, Ortigas Center, Mandaluyong City.
The Key Macroeconomic Highlights of the Overview of Global Shockwaves, Local Impacts are GDP Driver Slowdown, Inflation Spike and Interest Tightening, Employment Decline, Credit Rating Tempering and Piecemeal Peace.
Year-on-Year GDP Growth continues to decline from 2022 to 2026 Q1. Inflation is accelerating; policy rate increases to follow from 2021 to 2026 Q1. Employment rate reaches annual post-pandemic low from 2024 to 2026 Q1. OFW remittance are expected to decline 7.8% in 2026. Credit Rating Agencies downgraded their outlook for the Philippines .
PEZA surpasses its full-year 2025 investment target. Foreign direct investments decline by 17.1% YOY in 2025. The Philippines’ purchasing power eroded at the quickest pace among the ASEAN-5.
Regardless of the war outcome, the impact is predictable. Will the ceasefire hold? Scenario 1: Peace, Scenario 2: Escalation, and Scenario 3: Uneasy Ceasefire. The General Impact include Economic Slowdown, Accelerated Inflation, Short-Term Storage Demand Spike, Wait-and-See Approach and Shift Toward Renewable Energy.
Wait and See: What Geopolitical Conflict Means for the Industrial Sector
Steady Supply Growth to 2028, Downtick in Occupancy in 2026Q1, Flight to quality for Grade A Facilities, Lease Rates Remain Stable, and Transportation Logistics Dominate Industrial Requirements are the Key Highlights for the Industrial Sector.
Batangas market recovers from dip as other provinces remain stable in relation with the Quarterly Warehouse Occupancy Levels per Major Corridor from 2025Q1 to 2026Q1.
Lease rates experienced minimal changes from 2025Q4 to 2026Q1. Wholesale/Retail demand tapered off following 2025H2 as Laguna continues to top charts for requirements. Industrial warehouse lease rates have yet to follow suit as the CMPI soars due to worldwide tensions.
Supply expansion and evolving lease strategies are expected to define the Philippine Industrial market for 2026.
Recuperation Amid Rising Competitive Pressure
Key Highlights for Metro Manila’s Office Sector include No major shocks in Q1, CBDs marginal softening, Typical Demand Drivers, Decentralization & Cost Shift, and Incoming Supply Pressure.
Occupancy in Metro Manila is expected to progress gradually while new supply enter the market. Each CBD displayed varying occupancy changes QoQ amidst minimal completions. Occupancy mostly held steady in Q1 21026 in Metro Cities (Makati CBD, BGC, Ortigas CBD, Quezon City, Bay Area, Alabang CBD).
Metro Manila CBD’s exhibited a mixed lease rate performance in Q1 2026. BGC/Makati has the Widest Rage with Ceiling Price of PHP 1,800/SQM. Alabang CBD (PHP 500 Spread)has the Tightest Range with Lowest Rate of PHP 350/SQM.
Requirements in Q1 2026 were concentrated in CBD’s attractive to BPO and Gov’t.
Office demand remains expansion-led
Leasing Behavior – Demand is driven by expansion (60) rather than relocations. Hybrid and flexible arrangements were adapted particularly by the government sector, while private firms revert to dedicated setups, treating flexibility as tranasiitonal.
Lease Terms and Preferences – Standard lease terms remain around 3 years to 5 years with some tenants preferring 5-year terms. Rising construction and fit-out costs have pushed tenants toward fitted spaces.
Market Shifts and External Pressures – Decentralization remains additive, with firms expanding beyond core CBDs. BPO growth outside Metro Manila is concentrated in established Tier 1 and Tier 2 cities, as security, infrastructure, and incentive gaps temper Tier 3 confidence. The Fuel Crisis has impacted tenant decision and deal timelines, not negotiated lease rate.
Cautious optimism shapes Metro Manila’s office market outlook for 2026.
Office supply in Metro Manila is expected to grow by approximately 2.2% by the end of 2026. Tenants are increasingly preferring fitted office spaces due to rising construction costs. Occupancy is projected to improve gradually by around 1% driven by continued BPO expansion. BGC and Makati are expected to experience stable to moderate rental growth.
Beyond the Metro: The Decentralization Playbook
What Top Developers See in VISMIN
Competitive wages and significant population growth supports long-term growth prospects. VISMIN has a growth-investment gap. 2025 PH Regional Investment Share, GDP Growth, and Total Population
Different Strokes: The Diverging Trajectories of Cebu’s Key Sectors
High leasing velocity is expected for new office developments as older developments perpetuate majority of 13.2% vacancy. Robust office pipelines are expected to accelerate 2026’s lease rate growth. Continues demand and influx of new warehouse sustain warehousing lease rate growth. The Warehouse Demand by Industry in Cebu (2025) of the 44,000 SQM include Manufacturing (28%), Transportation and Storage (27%), Wholesale and Retail Trade (25%) and Others (20%). At 2% vacancy, Cebu’s cold storage market has never been tighter.
Industrial decentralization is creating hotspots in Cebu.
From Cane to Capital: Why Major Developers are Betting Big on Bacolod
Retail giants are converging on Bacolod, with approximately 100,000 sqm of new mall space expected to enter the market within the next three years.
Solid economic fundamentals have attracted significant developer interest. GDP Growth of Highly Cities in Visayas (2024) The cities: Tacloban City (8.20%), Bacolod City (7.70%), Iloilo City (7.10%), Mandaue City (6.90%) snd Lapu-Lapu City (6.5%). National Average: 5.7% Population by Highly Urbanized City in Visayas (2024) include Cebu City (965K), Bacolod City (625K), Lapu-Lapu City (498K), Iloilo City (474K), Mandaue City (364K) and Tacloban City City (259K).
The 100,000 sqm of new retail space of Robinsons Place Bacolod, Megaworld Upper East Mall and Rockwell Power Plant Mall will be introduce within 3 yrs.
Office occupancy at 74.7% leaves a lot to be absorbed, but newer developments exhibit remarkable absorption underpinned by demand chiefly from the IT-BPM sector. IT-BPM Companies Present in Bacolod City inclide concnetrix, Transcom, pentagon, TQVS, APEXREVA, iqorCXBPO, HitRate, Next Level IT Teleservices, SERV CE FIRST, GlobalStrategic, T, ttec, and PROMINENT OUTSOURCE.
Bacolod’s warehousing quality gap keeps lease rates on the lower end.
Green All-Around: Why Mindanao is Set For Monumental Growth
Anchored by a well-established IT-BPM sector that accounts for roughly 75% of office requirements, Davao is poised to swiftly absorb the approximately 85k sqm of new office space expected to complete within the next four years.
CDO & Davao are the most fiscally productive HUC per capita in Mindanao. New office developments will break a 5-year streak of inactivity.
With a saturated downtown, an emerging uptown is sprouting. Downtown Retail Developments in Cagayan de Oro include SM CITY CDO, Gaisano Mall, Centrio Mall, Limketkai Mall, Robinons and All Home.
85k sqm of grade A office space will be introduced from 2026-2029. Davao is statistically the only landlord’s office market. IT-BPM expansion is the key driver of Davao’s office market. Office Occupants in Davao City (2026Q1) include IT-BPM (25%) and Traditional (75%) for the 284,000 SQM. Further rent segmentation will follow introduction of new developments. Davao posts one of the lowest warehouse nationwide at 2.4% with rent appreciation expected to follow. Temperature-controlled logistics have responded to rising port activity.
VISMIN markets are expected to improve, each at their own pace
CEBU – Robust office pipelines are expected to accelerate office lease rate growth beyond 2.4% and furthers segment premium vs. non-premium markets. Decentralization of newer supply is slated to create new hotspots in the Cebu Fringe, Southern Cebu, and other areas as vacancy is at its tightest.
BACOLOD – The additional 100k sqm of mall space in the next 3 years will intensify pressure against local developments. The completion of Panay-Guimaras-Negros Island Bridges will help alleviate ferry dependency and create a new industrial hotspot in Pulupundan.
DAVAO – New Grade A office completions (2026-209) amounting to 85k sqm will trigger a flight-to-quality cycle attracting new entrants into the market. Further warehouse completions are likely to delayed by rising construction cost (30%+) further prolonging the landlord’s market.
CDO – The Uptown Corridor will emerge as CDO’s primary zone for commercial growth with the influx of various township developments. Port-linked cold storage demand is expected to grow as the Mindanao Container Terminal continuous to be over capacitated and upgraded.
PRIME Philippines moves your business forward by incorporating the most innovative solutions to your ever-changing real estate needs. A real estate consultancy firm ready to provide your business with solutions regardless of the stage you are in.
REFERENCE: PRIME Philippines, PRIME Philippines Research & Advisory Group
On April 30, 2024, I attended through online via Zoom of the BPI Foundation and Bayan Academy Sinag Synergy “Lakas sa Pagsanib-pwersa at Kulturang Bayanihan”, Preserving Culture: Promoting Social Entrepreneurship Pursuing National Development.
Mr. Adrian M. Tamayo, Phd, MPSA, Chief, Public Relations Division & Focal for Research, Futures Thinking and Analytics, delivered the Social Entrepreneurship for Peacebuilding, Reconcilation and Development: Mindanao. With regards of Mindanao: The Country’s Food Basket, Mindanao comprises 36% of the country’s farmland and Mindanao contributes to 42% of the nat’l. food trade. The Mandate (Republic Act No. 9996): Advancing Mindanao CHI as follows: 1. Coordination – Mindanao-wide initiatives Philippine Coordinating Office for BJMP-EAGA (PCOBE); 2. Harmonization – Efforts with a Mindanao-wide perspective; and 3. Integration – Mindanao agenda.